Top Guidelines Of Kam Financial & Realty, Inc.
Table of ContentsSome Known Questions About Kam Financial & Realty, Inc..Kam Financial & Realty, Inc. for DummiesFascination About Kam Financial & Realty, Inc.Little Known Questions About Kam Financial & Realty, Inc..Not known Facts About Kam Financial & Realty, Inc.What Does Kam Financial & Realty, Inc. Do?How Kam Financial & Realty, Inc. can Save You Time, Stress, and Money.
Getting a home is a major turning point in several individuals's lives. That doesn't suggest the procedure is clear to those individuals (mortgage loan officer california). The home getting procedure includes many steps and variables, indicating each individual's experience will certainly be distinct to their family members, financial circumstance, and wanted home. However that doesn't mean we can't aid make sense of the home loan procedure.A is a kind of financing you make use of to acquire residential property, such as a home. A monetary establishment or "lender" will certainly offer you cash and they will certainly need you to make use of the home as collateral. This is called a protected car loan. Usually, a loan provider will offer you a set amount of cash based on the value of the home you want to acquire or have.
The 9-Minute Rule for Kam Financial & Realty, Inc.
To certify for a home loan, you will require to be at the very least 18 years old. Aspects that help in the home mortgage process are a trusted revenue source, a strong debt score, and a small debt-to-income ratio. https://issuu.com/kamfnnclr1ty. You'll find out more about these consider Module 2: A is when the house owner obtains a new mortgage to change the one they currently have in location
A features likewise to a very first home loan. An operates a little bit in a different way from a traditional mortgage financing and is comparable to a credit rating card.
This co-signer will certainly agree to pay on the home mortgage if the debtor does not pay as agreed. Title companies play an essential function guaranteeing the smooth transfer of building ownership. They research state and region documents to confirm the "title", or possession of your house being acquired, is totally free and free from any kind of various other mortgages or obligations.
Getting The Kam Financial & Realty, Inc. To Work
In addition, they provide written assurance to the loan provider and produce all the documentation needed for the mortgage. A down settlement is the amount of money you must pay ahead of time towards the purchase of your home. If you are buying a home for $100,000 the lending institution might ask you for a down settlement of 5%, which means you would certainly be required to have $5,000 in cash as the down repayment to purchase the home. https://pubhtml5.com/homepage/cvmae/.
The principal is the amount of cash you get from the lending institution to acquire the home. In the above instance, $95,000 would certainly be the amount of principal. Many lenders have conventional home loan guidelines that enable you to obtain a certain portion of the worth of the home. The percent of principal you can obtain will certainly vary based on the home mortgage program you qualify for.
There are special programs for newbie home buyers, veterans, and low-income customers that permit lower down payments and higher percents of principal. A mortgage banker can examine these choices with you to see if you qualify at the time of application. Interest is what the lender fees you to borrow the cash to acquire the home.
See This Report on Kam Financial & Realty, Inc.
If you were to secure a 30-year (360 months) mortgage and obtain that same $95,000 from the above instance, the overall quantity of rate of interest you would pay, if you made all 360 regular monthly settlements, would be a little over $32,000. Your regular monthly settlement for this financing would be $632.
The majority of lenders will need you to pay your tax obligations with your home loan payment. Residential or commercial property tax obligations on a $100,000 car loan can be about $1,000 a year.
Some Known Facts About Kam Financial & Realty, Inc..

Again, due to the fact that the home is seen as security by the lending institution, they intend to make certain it's protected. Homeowners will certainly be called for to offer a copy of the insurance policy to the lending institution. The annual insurance plan for a $100,000 home will set you back roughly $1,200 a year. Like taxes, the loan provider will likewise offeror sometimes requireyou to include your insurance coverage premium in your monthly payment.
Your repayment now would certainly raise by $100 to a new overall of $815.33$600 in principle, $32 in rate of interest, $83.33 in taxes, and $100 in insurance policy. The lender holds this cash in the same escrow account as your residential property taxes and pays to the insurer in your place. Closing prices describe the costs related to refining your finance.
Things about Kam Financial & Realty, Inc.
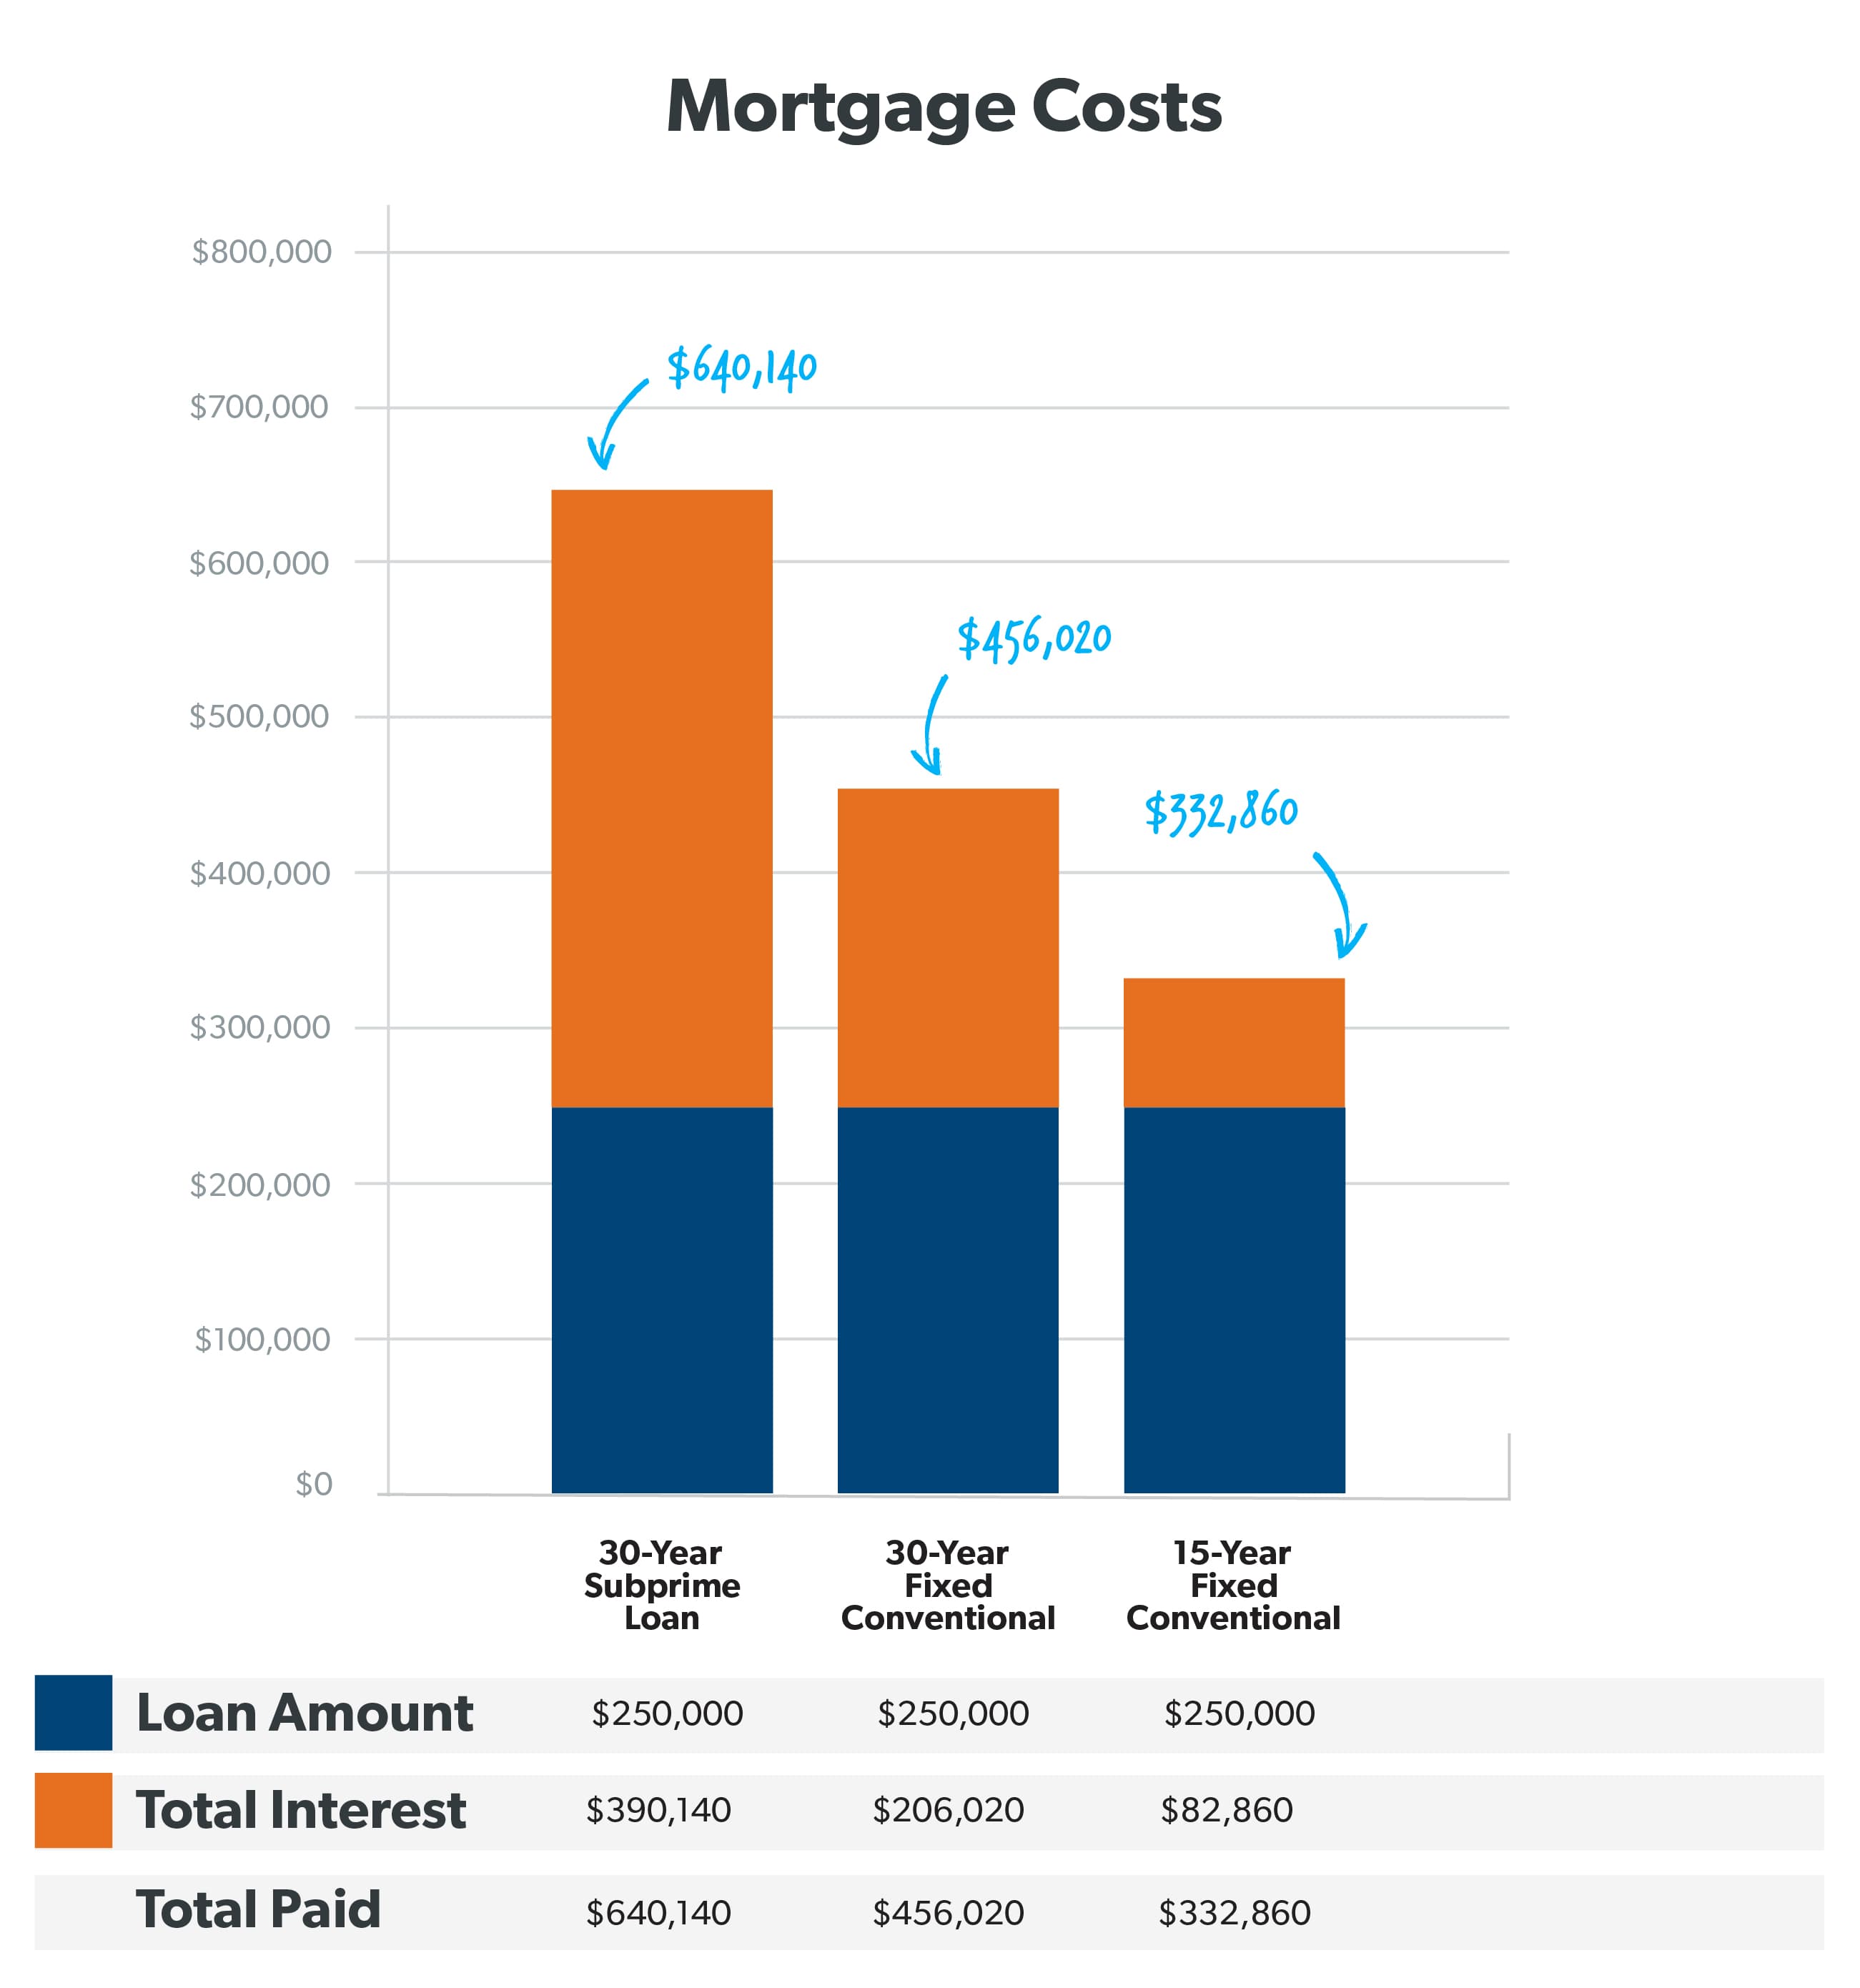
This guarantees you comprehend the total price and consent to proceed prior to the financing is funded. There are numerous various programs and lenders you can pick from when you're buying a home and obtaining a mortgage who can aid you navigate what programs or options will work best for you.
4 Easy Facts About Kam Financial & Realty, Inc. Explained
Numerous banks and realty agents can help you understand visit just how much money you can spend on a home and what financing amount you will get approved for. Do some research, yet additionally ask for referrals from your family and friends. Finding the best companions that are an excellent fit for you can make all the difference.
Comments on “Kam Financial & Realty, Inc. Fundamentals Explained”